Website Design for Mortgage Brokers in Sydney

Websites for Sydney mortgage and finance brokers, whether you hold your own credit licence or write loans under an aggregator: licence details where borrowers check them, a first home buyer page built around the NSW thresholds, and a quick route from “we're bidding on Saturday” to a call with you.

What a Sydney broker's website needs

Most people who land on a Sydney broker's site are partway through something: a first home priced near the NSW duty thresholds, an auction at the weekend, an apartment bought off the plan that settles next year, a refinance after a fixed rate ends. The site does its job when each of them can see within a screen or two that you handle their situation, that you're licensed, and how to get onto your calendar.

  • A licence line that matches ASIC's register

    Moneysmart tells borrowers to look a broker up on ASIC's Professional Registers before they meet. So the footer of every page carries exactly what that search will return: your credit representative number with your licensee's name and Australian Credit Licence number, or your own ACL number if you hold one. Your licensee supplies the wording and we copy it as given.

  • A NSW first home buyer page with dates on it

    First home buyers arrive asking what they'll pay in transfer duty and which schemes they can use. A page in your own words that names the First Home Buyers Assistance Scheme, the First Home Owner Grant for new homes and the federal 5% Deposit Scheme, shows the date you last checked each one and links to the official calculators, answers that without reading like personal advice.

  • A route for buyers heading to auction

    In NSW an auction buyer signs and pays the deposit on the day, so the question they bring you is pressing: how high can we go? A short form asking for the auction date, the suburb and whether they already hold a pre-approval lets you tell next month's enquiry from this Saturday's. Identity documents stay out of it.

  • Lenders and commission, stated plainly

    Borrowers who've read Moneysmart's checklist will ask which lenders you use and how you're paid. Name the lenders you're accredited with now, explain upfront and trail commission in two sentences, mention any fee you charge, and link the Credit Guide your licensee issues. When your panel changes, editing the list is covered by hosting.

  • Where and how you meet

    Sydney is a long drive from end to end, and a family in Penrith wants to know before booking whether you'll come to them, see them at an office in Parramatta or talk by video. One line near the top, such as “office in Hornsby, video appointments anywhere in NSW”, settles it better than a long list of suburbs.

  • The languages your brokers speak

    At the 2021 Census about two in three NSW residents used only English at home; after English came Mandarin (3.4%), Arabic (2.8%), Cantonese (1.8%) and Vietnamese (1.5%). Plenty of borrowers would rather go through a loan contract in their first language. Put each broker's languages beside their photo. Translation isn't something we offer, but send us text in another language and we'll set that page out like the English ones.

  • A call-back form and a booking button

    Name, mobile, what the loan is for (buying, refinancing, building or investing), rough timing and the best time to ring. The booking button opens the calendar tool you already use. Payslips, bank statements and ID go through your aggregator's or CRM's secure fact-find, never a website form or an email inbox.

Broking in Sydney: NSW thresholds, auctions and off-the-plan buyers

The national rules first. Credit licensing is federal, so a broker in Chatswood works under the same National Consumer Credit Protection Act obligations as one in Adelaide: the best interests duty, a Credit Guide, licence numbers that match ASIC's registers, a comparison rate beside any advertised home loan rate, and limits on calling yourself “independent”. Our main mortgage broker page sets those out. What's different in Sydney is the state layer on top: NSW duty, NSW grants and the way property changes hands in NSW.

First home buyer thresholds. For contracts exchanged from 1 July 2023, Revenue NSW's First Home Buyers Assistance Scheme gives a full transfer duty exemption on a new or existing home valued at $800,000 or less, and a concessional rate above that and below $1 million; for vacant land the figures are $350,000 and $450,000. The buyer has to move in within 12 months of settlement and live there for at least 12 continuous months. The $10,000 First Home Owner Grant covers new or substantially renovated homes only: up to $600,000 for a newly built or renovated home, or $750,000 for a house-and-land package with a building contract. The federal 5% Deposit Scheme, which has had no income caps and no lenders mortgage insurance since 1 October 2025, caps prices at $1.5 million in Sydney and the NSW regional centres, which include the Central Coast, the Illawarra and Newcastle and Lake Macquarie, and at $800,000 in the rest of the state. So a $900,000 apartment sits above the full duty exemption, inside the concession band and well under the scheme cap: the kind of overlap you explain on a call. The website's job is to name the schemes, link to Revenue NSW's calculators (opens in a new tab) and the scheme's price caps (opens in a new tab), and show when you last checked them.

Auctions. NSW Fair Trading's auction guide is direct about it: there is no cooling-off period when you buy at auction, a deposit of usually 10 per cent is paid on the spot, and a buyer who can't complete loses it. It tells bidders to confirm with their lender the most they can borrow, stamp duty included, and to have approvals in place before bidding. For a Sydney broker that puts pre-approval near the centre of the site: a page explaining what a pre-approval is and how you arrange one, in your words, and an enquiry form that asks for the auction date so a Thursday-night message about Saturday reaches you first. Bidder registration, with its proof of identity, happens with the selling agent rather than on your site.

Off-the-plan and overseas buyers. Two more NSW rules shape what some Sydney brokers need to say. Owner-occupiers buying a home off the plan can apply to defer transfer duty for up to 12 months, with duty then due at the earliest of 15 months after the contract, settlement or assignment; the deferral isn't automatic and is limited to Australian citizens and certain residents who intend to live in the home. A foreign person buying residential property in NSW pays surcharge purchaser duty, currently 9% of the dutiable value, on top of transfer duty, and Revenue NSW generally treats temporary and bridging visa holders as foreign persons. If you work with apartment buyers or temporary residents, a page that says so plainly helps the right borrowers find you. We'd leave the eligibility detail to links, because it's Revenue NSW's to state and to change.

How we work with Sydney brokers. We're an Adelaide team on Hutt St and work with Sydney businesses by phone and email. Our Sydney clients include Resolve Forward, a family dispute resolution practice; we haven't built a mortgage broking site yet, and we'd rather you heard that from us. Your licensee's compliance team can review the draft link before anything goes live, and you pay nothing until the site is approved.
Booking and intake work that carries over

There's no mortgage broker in our portfolio yet. These two sites do the jobs a broker's site leans on most: taking someone from a first look to a booked call, and setting out credentials clearly before they book.

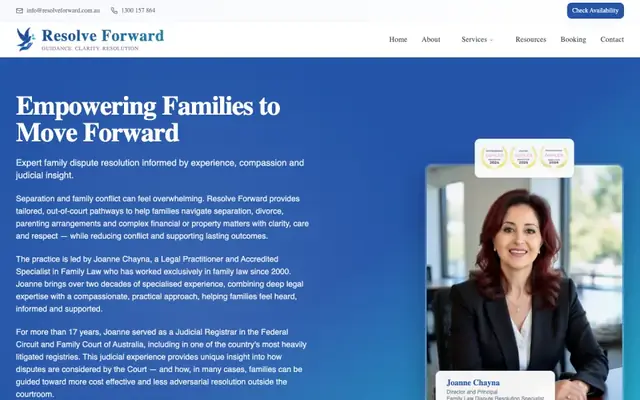
Home page of the Resolve Forward website

Resolve Forward

Professional services · Sydney

One of our Sydney clients, a family law dispute resolution practice. Each priced package links to online booking, and the site carries a five-step intake form. A broker's call-back form that asks for loan purpose, timing and auction date before the first call does a similar job.

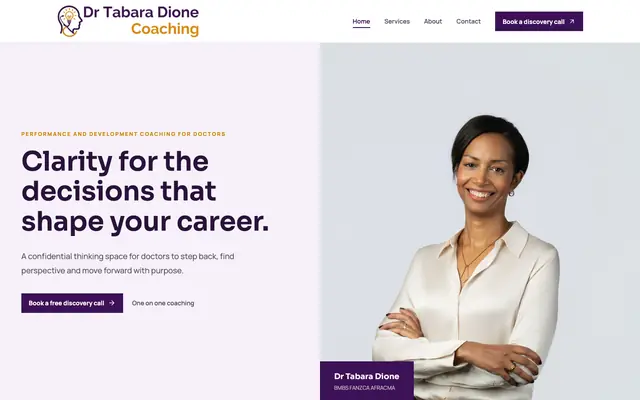
Home page of the Dr Tabara Dione Coaching website

Dr Tabara Dione Coaching

Professional services · Melbourne

A Melbourne specialist anaesthetist who coaches doctors. Her about page sets out her credentials, and a link on every page books a discovery call online: the same pairing a broker needs between a licence line people can verify and a “book a call” button.

“Salem created a sleek, professional website for www.resolveforward.com.au with an intuitive and easy-to-use bookings page.”

Resolve Forward, Google review

What a broker's website costs in Sydney

One page

$399

A solo broker: who you help, your lenders and commission, the licence line, where you meet, a booking button and a call-back form.

Our suggestion for most Sydney brokers

Up to 3 pages

$899

A home page, a first home buyer page naming the NSW schemes with dated links, and a “how we work” page on pre-approval, auctions and how you're paid.

Up to 8 pages

$1,499

For a brokerage: a profile with languages for each broker, plus pages for first homes, auction buyers, off-the-plan, refinancing, investors and self-employed borrowers.

  • Payment. No deposit. We build your draft first, you ask for as many changes as you like, and you pay once you approve it. If you don't go ahead, you owe nothing.
  • GST. WebCraft Studio isn't registered for GST, so no GST is added.
  • Timing. Most sites are live within 5–10 days of us getting your words and photos; bigger sites (up to 8 pages) take 2–3 weeks.
  • Hosting. After launch, hosting is $30 a month: hosting, security monitoring, backups, email support and unlimited text and image changes on your existing pages. New pages or features are quoted first. No contract, cancel anytime.
  • Domain and email. We register your domain in your name (about $20 a year), connect it to your site and set up your business email.

See full pricing and what each package includes

Questions Sydney brokers ask us

Should our site quote the NSW stamp duty and grant thresholds?

You can, provided each figure is dated and links to its source. They do move: Revenue NSW still lists the earlier version of the first home buyer scheme, when the full exemption stopped at $650,000, which applied to contracts up to 30 June 2023. Some brokers prefer to name the schemes, link the official calculators and leave exact numbers for the first conversation. Either way, changing a figure later is a text edit that our hosting covers.

Can buyers ask for pre-approval before an auction through the site?

They can send the request: a form with the suburb, the auction date, roughly what they hope to spend and whether they've already spoken to a lender. It reaches your inbox at once, with the auction date near the top of the email so it stands out. The assessment itself, and anything like payslips or ID, goes through your usual fact-find, and the page never promises an approval or a turnaround you don't control.

We mostly help people buying off the plan. What should the site say?

Who you help and what you do for them, in your own words, with links to Revenue NSW for the rules. The off-the-plan duty deferral comes with conditions on citizenship or residency, living in the home and applying for it, and buyers who are foreign persons may owe surcharge purchaser duty as well. The site can list these as things to bring up on the first call, and your licensee can check the wording before launch.

We're credit representatives under an aggregator. Who signs off the site?

Ask your licensee first. ASIC says licensees have a continuing obligation to monitor and supervise their representatives, so check whether yours wants to see the site before it goes live. We send a draft link you can forward to their compliance team, make whatever changes they ask for, and use their licence and disclosure wording exactly as supplied. You pay once the site is approved.

Can the site have a stamp duty or repayment calculator?

Revenue NSW publishes a Transfer of Land or Business Calculator and a First Home Buyer Assistance Scheme Calculator, and Moneysmart has a mortgage calculator. Linking those keeps the numbers right without you maintaining them. If you'd like a custom calculator built into your own site, we quote it first like any feature, and one where visitors enter their own interest rate avoids putting an advertised rate on the page.

You're based in Adelaide. How does a Sydney brokerage work with you?

Entirely by phone and email. WebCraft Studio is an Adelaide (South Australia) team building sites for businesses around Australia, with current clients in SA, NSW, VIC and QLD; Resolve Forward is one of our Sydney clients. You send your words, broker headshots, licence details and lender list, we build the draft, and you pay when you're happy with it. We reply within 24 hours.

Planning a website for your Sydney brokerage?

Tell us your licence or credit representative details, the borrowers you mostly help and how they book with you now. We'll quote it, build a draft your licensee can review, and you pay once it's approved.

We reply within 24 hours. Prefer email? info@webcraftstudio.com.au