Website Design for Mortgage Brokers in Brisbane

Websites for Brisbane mortgage and finance brokers, licensed in your own name or writing loans under an aggregator: a licence line borrowers can check against ASIC's register, a Queensland first home page that dates every grant and duty figure, and an enquiry form that tells you when a buyer's cooling-off period runs out.

What a Brisbane broker's site has to cover

Queensland has reworked its home buyer settings repeatedly since mid-2024: a higher duty threshold for established first homes in June 2024, no duty on new first homes and vacant land from May 2025, and a citizenship or residency test for the home concessions from August 2026. Borrowers turn up having read some of that, and part of what they read is out of date. A broker's site is useful when it shows who you help, proves you're licensed, makes clear your information is current, and then gets them on the phone.

  • Licence and membership details people can check

    Moneysmart suggests borrowers search ASIC's Professional Registers before they meet a broker, so the footer of each page carries what that search will show: your own Australian Credit Licence number, or your credit representative number alongside your licensee's name and ACL. If you belong to the FBAA, whose national office is at Eight Mile Plains on Brisbane's southside, or to the MFAA, we add the member artwork your association supplies, used the way it says.

  • A Queensland first home page with a checked-on date

    One page, in your words, naming what a Brisbane first home buyer might use: the transfer duty concessions, the First Home Owner Grant for new homes, the federal 5% Deposit Scheme and the state's Boost to Buy. Each item links to its official page and shows the date you last checked it, so a reader can tell current information from a page nobody has touched since 2024.

  • An enquiry form that asks about deadlines

    Someone who has just signed a standard Queensland home contract has five working days of cooling-off, ending at 5pm on the last of them, and a winning bidder at auction has none at all. So the call-back form asks whether they've signed, on what date, and whether an auction is coming up, and that line leads the email you receive. Payslips, bank statements and ID stay out of it and go through your secure fact-find.

  • A page for buyers who are building

    From 1 May 2025 a Queensland first home buyer pays no transfer duty on a new home or on residential vacant land, with no value cap, and the state grant only applies to new homes. Both settings favour new builds, and people who build ask different questions: construction loans, progress payments, how a land contract and a building contract fit together. A page on how you handle those suits brokers who see a lot of them.

  • Who you can help after the August 2026 change

    For transactions from 1 August 2026, Queensland's home, first home and vacant land duty concessions require every buyer to be an Australian citizen, a permanent resident or a specified foreign retiree. If you work with temporary visa holders, or couples where one partner is on a visa, saying so near the top helps them find you before they budget on numbers that no longer apply to them. Whether they qualify is for QRO and your advice, not the website.

  • Where you meet across the Brisbane region

    Brisbane borrowers are spread across several councils, from Moreton Bay in the north to Logan in the south and Ipswich in the west, and a couple in Springfield Lakes wants to know before booking whether you'll come to them, see them at an office in Chermside or talk by video. One line near the top settles it, and the booking button opens the calendar tool you already use.

Broking in Brisbane: Queensland duty, grants and deposit schemes

Federal rules, Queensland detail. Credit licensing is national, so a broker in Carindale answers to the same National Consumer Credit Protection Act as one in Perth: the best interests duty, a Credit Guide, licence numbers that match ASIC's registers, and a comparison rate wherever a home loan rate is advertised. Our main mortgage broker page covers those, and our Sydney broker page shows how a state's own duty rules change what a site needs. In Brisbane that state layer is Queensland duty, the Queensland grant and a state equity scheme, and the details keep moving.

Transfer duty and the grant. For an established first home, the Queensland Revenue Office's first home concession (opens in a new tab) means no duty at $700,000 or less for agreements from 9 June 2024, and a reduced amount for homes valued under $800,000; QRO's own worked example puts the duty on a $730,000 home at $6,555. A first home buyer signing on or after 1 May 2025 for a new home or residential vacant land pays no duty on the home and its residential land, whatever the value. The First Home Owner Grant is $30,000 for a new home valued under $750,000 including land, and the 2026 state budget kept that increased amount for eligible contracts signed from 1 July 2026. Then, for transactions entered into from 1 August 2026, those concessions are limited to Australian citizens, permanent residents and specified foreign retirees. A broker's site shouldn't try to restate all of it: name the concessions, link QRO's transfer duty estimator (opens in a new tab), and print the date you last checked.

Three low-deposit routes with different front doors. The federal 5% Deposit Scheme caps prices at $1,000,000 in Brisbane and in the two Queensland regional centres it lists, the Gold Coast and the Sunshine Coast, and at $700,000 in the rest of the state. Since the 1 October 2025 changes it has no income caps or waitlists and buyers pay no lenders mortgage insurance, and they apply only through a participating lender. Queensland's Boost to Buy (opens in a new tab) takes an equity share of up to 30% in a new home or 25% in an existing one, with a 2% deposit, a purchase price of $1 million or less, and income limits of $155,000 for a single adult and $232,000 for two. One lender, Unity Bank, takes part, and Treasury's page, last updated on 30 September 2026, says South East Queensland's round 2 allocations are exhausted. Places go by where the property is, not where the buyer lives, and Treasury's regional allocation guideline (opens in a new tab, PDF) counts the Brisbane, Ipswich, Logan–Beaudesert and Moreton Bay regions, plus the Gold Coast and Sunshine Coast, as South East Queensland, while Toowoomba and the Darling Downs are regional. So for now a home in greater Brisbane can't get a place, but a Brisbane client buying in Toowoomba might. The state's own Housing Finance Loan, with deposits from 2% and a household income limit of $141,000, is applied for directly through the Queensland Government's housing department. A schemes page that says which of these you can help with, which you can't and where each one stood when you last checked does more for a borrower than a row of logos.

Signing a contract in Queensland. The state's cooling-off rules (opens in a new tab) give a buyer on the standard contract five working days, starting the day they receive a copy signed by both sides and ending at 5pm on the last day, and a buyer who pulls out can be charged up to 0.25% of the price. There's no cooling-off at auction, or on a private contract a registered bidder signs within two working days of an unsuccessful auction, and the government's auction guide (opens in a new tab) says the terms usually require an unconditional bid. The same advice suggests insuring the home from the contract date in most cases, and in Brisbane the flood question comes up early: Brisbane City Council's Flood Awareness Map (opens in a new tab) gives general flood information for an address, though only inside the Brisbane council boundary. On a broker's site that becomes a short “before you sign” page with those links and the signing-date question on the enquiry form, rather than anything resembling legal advice.

Working with us from Brisbane. We're an Adelaide team on Hutt St and work with Queensland businesses by phone and email; our clients there include a dance school at Thorneside on the bayside and a Queensland plumber and gas fitter. We haven't built a broking site yet, and we'd rather you heard that from us. Your licensee's compliance team can go through the draft link before launch, and nothing is owed until you approve the site.
Queensland and booking work to compare

No mortgage broker sits in our portfolio yet. One of these sites is for a Brisbane business with a page for each program and a form that gathers details before the first conversation; the other turns a first look into a booked appointment.

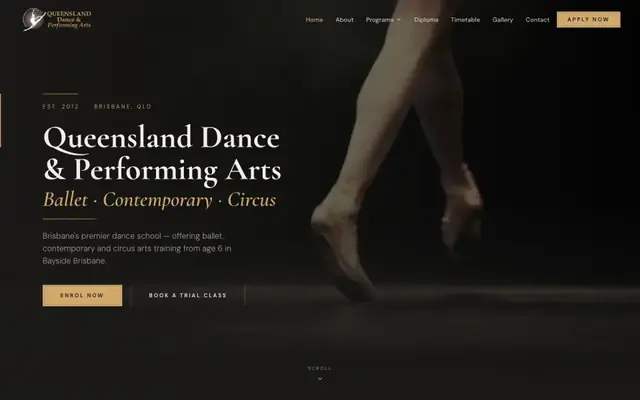
Home page of the Queensland Dance & Performing Arts website

Queensland Dance & Performing Arts

Community, creative & tourism · Thorneside, Brisbane's Bayside

A dance and performing arts school at Thorneside, on Brisbane's bayside. Its 12 pages include one for each program and the full-time diploma, a weekly timetable, a filterable gallery, FAQs and an online enrolment form. On a broker's site the programs become borrower types (first home, building, refinancing, investing) and the enrolment form becomes a call-back request.

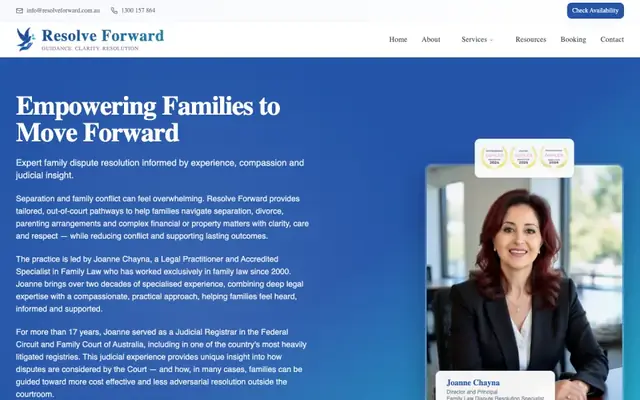
Home page of the Resolve Forward website

Resolve Forward

Professional services · Sydney

A Sydney family dispute resolution practice where every priced package leads to online booking, and a five-step intake form collects the basics first. A broker's “book a call” button, with a few questions about signing dates and auctions before it, follows the same path.

“Rebuilt two websites for our businesses and saved us a fortune on hosting etc. Nothing is ever a problem, will email back on a Saturday night if need be.”

Lockyer Valley Batteries, Google review

What a Brisbane broker's website costs

One page

$399

A solo broker: the borrowers you help, lenders and commission, your licence line, where you meet, and a call-back form that asks about signing and auction dates.

What we'd suggest for most Brisbane brokers

Up to 3 pages

$899

Home, a dated Queensland first home page (duty, the grant, the 5% Deposit Scheme, Boost to Buy) and a “before you sign” page on pre-approval, cooling-off and auctions.

Up to 8 pages

$1,499

For a brokerage: broker profiles, plus pages for first homes, building a new home, refinancing, investors, self-employed borrowers and temporary residents.

  • Payment. No deposit. We build your draft first, you ask for as many changes as you like, and you pay once you approve it. If you don't go ahead, you owe nothing.
  • GST. WebCraft Studio isn't registered for GST, so no GST is added.
  • Timing. Most sites are live within 5–10 days of us getting your words and photos; bigger sites (up to 8 pages) take 2–3 weeks.
  • Hosting. After launch, hosting is $30 a month: hosting, security monitoring, backups, email support and unlimited text and image changes on your existing pages. New pages or features are quoted first. No contract, cancel anytime.
  • Domain and email. We register your domain in your name (about $20 a year), connect it to your site and set up your business email.

See full pricing and what each package includes

Questions Brisbane brokers ask us

Should our site mention Boost to Buy when there are no Brisbane places?

Yes, if it's described accurately. Queensland Treasury's page says South East Queensland's round 2 allocations are exhausted, that regional places remain through Unity Bank, and that any future availability will be announced there. Places follow the property's location, so a client buying in Toowoomba or another regional area may still be able to apply. A short entry saying what the scheme is, that it's closed for Brisbane purchases at the time of writing, and linking to Treasury answers the question without raising hopes. When a new round opens, changing that text is covered by hosting.

Can we quote Queensland duty figures on the site?

You can, provided each one carries a date and a source. The established first home threshold changed on 9 June 2024, new homes and vacant land changed on 1 May 2025, and the citizenship and residency test applies from 1 August 2026, so a page written in early 2024 is already wrong. Plenty of brokers name the concessions and link QRO's transfer duty estimator instead, which QRO says gives an estimate only and is no substitute for professional advice.

Many of our clients hold temporary visas. What should the site say?

Who you help, in your own words, with a link to the Queensland Revenue Office. From 1 August 2026 the home and first home duty concessions need every buyer to be a citizen, permanent resident or specified foreign retiree, and Boost to Buy and the state's Housing Finance Loan are both limited to citizens and permanent residents. The site can list these as things to raise on the first call, and your licensee can check the wording before launch.

Can a buyer in cooling-off reach us quickly through the site?

The form can make their deadline hard to miss. It asks whether they've signed and on what date, and the email you get leads with that answer, so a contract signed on Tuesday doesn't wait behind general enquiries. Tap-to-call on mobile and your booking link sit beside it. The page shouldn't promise an approval inside the cooling-off period, because that depends on the lender and the borrower's paperwork, not on the website.

You're in Adelaide. How does a Brisbane brokerage work with you?

By phone and email. WebCraft Studio is an Adelaide (South Australia) team building sites for businesses around Australia, with current clients in SA, NSW, VIC and QLD, including a dance school on Brisbane's bayside. You send your words, headshots, licence wording and lender list; we build a draft link you can pass to your licensee, and you pay when it's approved. We reply within 24 hours.

Planning a website for your Brisbane brokerage?

Tell us who holds your credit licence, which borrowers you see most (first home buyers, people building, refinancers, investors) and how they reach you now. We'll quote it, send a draft your compliance team can review, and you pay only once you approve it.

We reply within 24 hours. Prefer email? info@webcraftstudio.com.au